
The seven types of companies and related arrangements covered here are sole proprietorships, partnerships, LLCs, C corporations, S corporations, trusts, and nonprofits. They differ in ownership, personal liability, taxes, and fundraising options. However, these labels are not interchangeable. S corporation status is a tax election, while a trust usually manages assets rather than operating as a conventional company.
At 1Byte, we favor a practical starting point: choose around your risks, owners, and funding plans, not a fashionable label. This U.S.-focused comparison will help you narrow the options before discussing state-specific details with an attorney and tax advisor.
7 Types of Companies and Business Entities to Compare
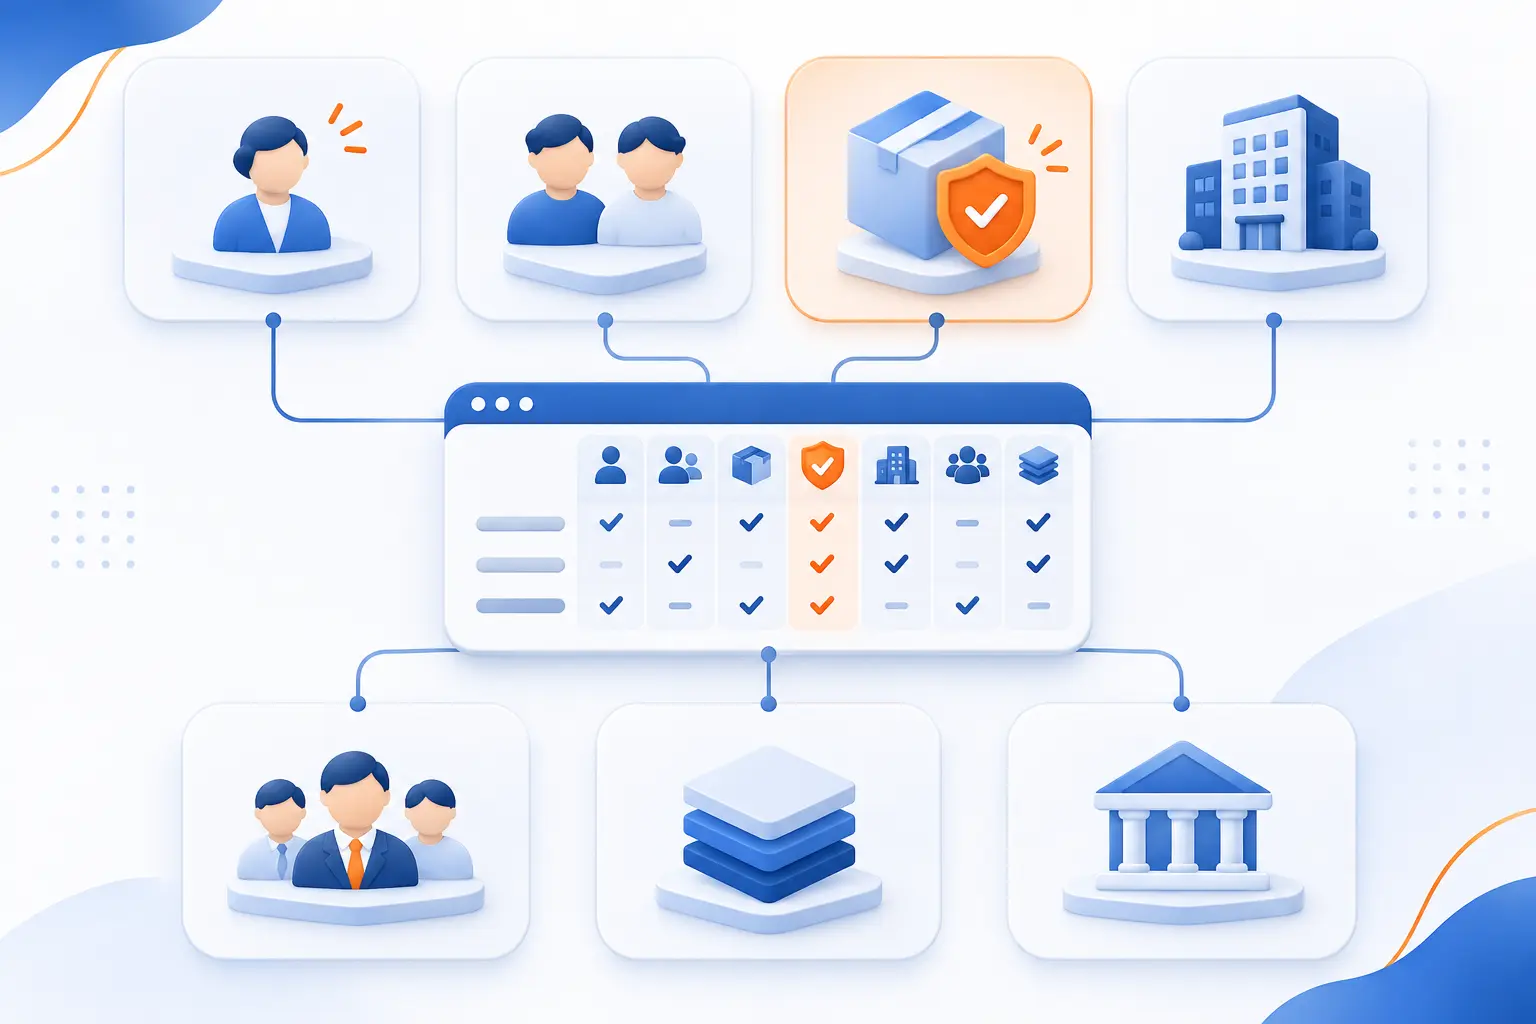
These seven options address different needs, from testing a solo business to raising investment or protecting a charitable mission. Use the table to shortlist possibilities, then examine their trade-offs below. Liability protection generally has exceptions, and federal tax treatment does not settle every state tax question.
| Option | Potential fit | Liability considerations | Typical federal income tax treatment |
|---|---|---|---|
| Sole proprietorship | Solo, relatively low-risk work | No separation between owner and business debts | Reported on the owner’s return |
| Partnership | Shared ownership or professional practices | Depends on general, limited, or LLP arrangement | Generally passes through to partners |
| LLC | Owner-operated businesses seeking liability separation | Members generally have limited liability | Default treatment depends on membership, with elections available |
| C corporation | Stock-based fundraising and broader ownership | Shareholders generally have limited liability | Corporate tax, plus shareholder tax on dividends |
| S corporation status | Eligible closely held businesses | Comes from the underlying legal entity | Generally passes through to shareholders |
| Trust | Asset stewardship and succession planning | Depends on the arrangement and applicable law | Depends on trust classification and distributions |
| Nonprofit organization | Charitable or other qualifying missions | Depends on legal form | Exemption requires meeting applicable requirements |
FURTHER READING: |
| 1. Zero Trust Network Access: How It Secures App Access |
| 2. What Is Enterprise Cloud Computing and How It Works |
| 3. Website Design Cost: What Businesses Should Budget |
1. Sole Proprietorships: Single Ownership, Simple Setup, and Personal Liability
Operating an unincorporated business alone generally leaves you and the business legally inseparable. This can suit a freelance editor or tutor testing demand without co-owners. Its appeal is simplicity, but business debts can expose personal assets. The owner generally reports business income through Schedule C with their individual return. We would weigh the actual work carefully before choosing this route. Simple paperwork does not make a risky activity safe.
2. Partnerships: Shared Ownership Through General, Limited, and Limited Liability Arrangements
Sharing ownership through a partnership makes liability allocation a central decision. This option can suit co-founders, investment arrangements, or eligible professional practices. General partners typically face personal liability for partnership obligations. Limited partnerships distinguish general partners from limited partners, while LLP protection depends on state law. For example, Texas permits an existing partnership to register for additional liability protection. We favor a written agreement before money changes hands, even when the owners are close friends.
3. Limited Liability Companies: Member Ownership, Liability Protection, and Tax Flexibility
Separating business obligations from members’ personal assets makes this a useful option for many owner-operated ventures. It can suit a solo consultant, online retailer, or small agency seeking liability protection without corporate ownership formalities. Federal taxation follows a separate decision. Depending on membership and elections, the business may receive disregarded-entity, partnership, or corporate treatment. We see flexibility as the attraction here, not automatic tax savings. Personal guarantees and an owner’s own misconduct can still create exposure.
4. C Corporations: Shareholder Ownership, Stock-Based Fundraising, and Double Taxation
Issuing stock through a separate legal entity can support outside investment and ownership transfers. This often fits founders pursuing institutional funding or a business with many shareholders. The trade-off includes formal governance and potential double taxation. Earnings are taxed again when distributed as dividends after corporate income tax. We would consider this structure when the funding plan justifies it, rather than treating incorporation as proof that a business has become serious.
5. S Corporations: Pass-Through Tax Status With Ownership and Eligibility Restrictions
Electing this federal tax treatment generally passes business income and losses through to eligible shareholders. It can suit closely held businesses whose owners meet the eligibility rules. The attraction is avoiding the usual C corporation dividend-tax pattern, but ownership is restricted. Requirements include no more than 100 shareholders, permitted shareholder categories, and a single class of stock. We treat this as a tax-planning discussion, not a substitute for choosing the underlying legal entity.
6. Trusts: Asset Management, Beneficiaries, and Estate-Planning Purposes
Placing property under a trustee’s management creates an arrangement for administering assets for beneficiaries. This can suit families planning succession or owners arranging long-term stewardship of business interests. Its value lies in controlling how assets are managed and transferred, not replacing everyday business formation. The defining relationship involves holding property for another’s benefit. We would involve an estate-planning attorney here because trust terms, tax classification, and state law shape the outcome.
7. Nonprofit Organizations: Mission-Based Operations and Tax-Exemption Requirements
Organizing around a mission rather than distributing profits to owners makes this suitable for charitable and other qualifying purposes. A community education program or animal rescue might consider this route. The benefit is a framework for pursuing that mission, potentially with tax exemption. However, state nonprofit formation does not automatically establish federal exemption. Charitable organizations must satisfy organizational and operational requirements. We would choose this path for the mission, never merely for the prospect of a smaller tax bill.
How to Match a Business Structure to Your Plans
Match your structure to personal exposure, decision-making, taxation, financing, and local requirements. The right choice should support how you expect the business to operate. We suggest comparing your strongest candidates against the same realistic business plan, rather than judging each in isolation.
Balance Startup Simplicity Against Personal Financial Exposure
Evaluate what a business claim could put at risk before choosing the easiest setup. We would compare a home-based writing service with a contractor entering customers’ properties. Their risks deserve different conversations. Ask an attorney where entity protection ends, especially around personal guarantees and your own actions. Include suitable insurance in that discussion rather than expecting formation paperwork to cover every loss.
Align Ownership and Management Rights With Your Co-Founders
Agree on decision-making rights before settling ownership percentages. We recommend discussing a concrete disagreement, such as whether to borrow money or admit another owner. Who gets the final say? Put the answer into the appropriate agreement. A balanced ownership split may feel fair, but we would not accept it without a workable plan for resolving deadlocks.
Evaluate Tax Treatment With a Qualified Advisor
Ask a qualified tax advisor to compare the total cost of each viable option using your expected earnings. Include owner payments, employment taxes, state obligations, and preparation costs in the comparison. We prefer a written estimate over a promise of tax savings. For an S election, ask specifically how owner compensation and payroll administration affect the result.
Consider Investor Expectations, Ownership Transfers, and Exit Plans
Discuss your intended funding and exit route before committing to an ownership structure. We would ask prospective investors what they can invest in and what rights they expect. Then test a sale, retirement, or co-founder departure against the proposed documents. The useful question is not whether you can start this way, but whether your likely next move remains practical.
Check State Rules and Industry-Specific Restrictions Before Deciding
Confirm eligibility with your state filing office and relevant professional regulator before submitting documents. We would be especially cautious with licensed services and businesses operating across state lines. Ask whether professional-entity requirements, ownership restrictions, or additional registrations apply. Do not assume another founder’s arrangement will work simply because you sell a similar service.
What to Prepare After Choosing Your Business Entity
Prepare a formation file, internal agreements, financial registrations, and a compliance calendar after choosing your entity. These preparations turn a structure on paper into an organized business. We recommend assigning responsibility for each area so that nothing disappears between a founder, accountant, and attorney.
Verify Business Name Availability and Required Formation Filings
Verify the proposed name and the exact filing requirements with the relevant state office. Depending on your entity, preparation may include formation documents and a registered agent. The official guidance explains that registration depends on structure and location. We would also investigate trademark conflicts before investing in branding. Treat a domain search as a separate task, not proof that you can legally use a business name.
Document Internal Rules Through Agreements or Bylaws
Put the rules for ownership and decision-making into documents appropriate to your entity. Ask counsel to address contributions, authority, distributions, departures, and disputes. We would also clarify ownership of business software, website content, and other intellectual property. The goal is practical: someone reviewing the records should understand who owns what and who can commit the business.
Arrange Tax Registration, Business Banking, Licenses, and Permits
Prepare a launch checklist with your accountant that covers applicable tax registrations, banking, licenses, and permits. Ask which identifiers and documents your particular business needs. We recommend keeping business transactions separate from personal spending from the start. For an online venture, also decide who will control payment accounts and retain the records needed for bookkeeping.
Plan for Annual Reports, Tax Filings, and Corporate Records
Create a compliance calendar with an accountable owner for every applicable deadline. State reports, tax returns, license renewals, and internal records serve different purposes. Official guidance distinguishes internal records from external filing obligations. We would store filing confirmations alongside the calendar. That makes it easier to establish what was submitted, rather than relying on someone’s memory when a notice arrives.
FAQ
These answers address common questions about choosing among types of companies in the United States. We use illustrative small-business examples alongside a documented ownership arrangement to make the distinctions concrete. Your own choice still deserves a state-specific review.
What Are Examples of Businesses Suited to Different Structures?
A solo tutor might consider a sole proprietorship, while a retailer might evaluate an LLC and an investment-seeking startup a C corporation. These are starting points, not industry requirements. For a real-world example of layered ownership, Patagonia describes voting shares held by its purpose trust and nonvoting shares held by the nonprofit Holdfast Collective. We would not mistake that specialized arrangement for a standard template for small businesses.
Can One Person Form an LLC?
Yes, a single owner can generally form a single-member LLC under state law. The owner is called a member, and legal formation remains separate from federal tax classification. We recommend confirming your state’s filing requirements and any professional restrictions before applying.
Can an LLC Elect S Corporation Tax Status?
Yes, an eligible LLC can elect S corporation tax treatment by filing Form 2553 and satisfying the applicable requirements. The election changes federal tax treatment, not the underlying state-law LLC form. We recommend reviewing eligibility, timing, owner compensation, and state treatment with a qualified tax advisor.
Can You Change Your Business Structure After Formation?
Yes, changing your business structure is often possible, but the method and consequences depend on your circumstances. A tax election differs from a legal conversion, merger, or asset transfer. We would review contracts, licenses, ownership documents, and tax consequences before making the change.


Conclusion
The best choice among these types of companies is the one that fits your risks, owners, financing needs, and purpose. We would not pay for unnecessary complexity, but we would not sacrifice appropriate protection for a simpler application.
At 1Byte, our view is straightforward: settle the ownership foundations before committing heavily to the business around them. Shortlist your strongest options, write down the trade-offs, and take that comparison to an attorney and tax advisor. Which structure supports both the business you are starting and the one you hope to build?